
Corning Incorporated: Wiring for the Future of AI
When you look under the hood of artificial intelligence, the conversation almost always starts with high-flying semiconductors, advanced software, or hyperscale cloud architecture. But as long-term investors here at Beese Fulmer, we know that physical infrastructure also dictates the speed of innovation. We believe Corning Incorporated (GLW) sits quietly at the center of this dynamic, providing the glass-based optical wiring required to transmit data across the technology stack.
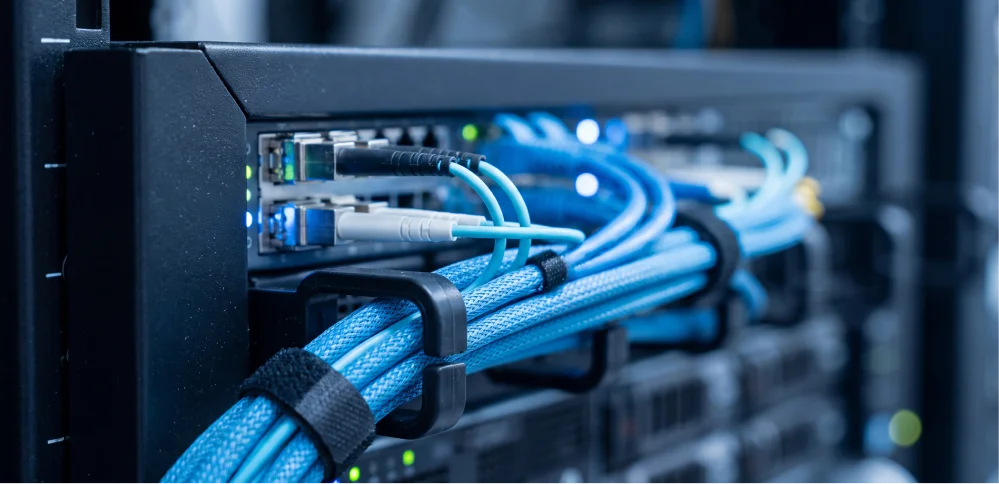
The rapid evolution of AI has created a physical bottleneck. Traditional data centers relied heavily on copper cabling inside and between server racks to move data. But as this technology has evolved to manage more data at greater speeds, copper is reaching its limits. It creates too much heat and becomes less effective as data speeds increase, making it difficult to keep pace with today's advanced semiconductor chips.
Corning is helping solve this bottleneck through its leadership in optical fiber. Instead of electrical signals over copper, Corning's specialized glass uses pulses of light to move massive amounts of data at extremely high speeds. More importantly, Corning is benefiting from a major structural shift in how AI data centers are being built. The industry is expanding beyond traditional "scale-out" connections, which link separate server racks, toward "scale-up" architecture that brings high-speed optical connections closer to the processors themselves. As AI clusters grow, this can dramatically increase the amount of optical content required. Simply put, more powerful AI systems need to move more data, and increasingly that data will move over glass instead of copper.
Long before AI data centers, Corning was known for its breakthroughs in specialty glass, producing products ranging from the glass used in Edison's light bulbs and Pyrex to Gorilla Glass, which is found in many of our electronic devices today. Global telecom companies also rely on fiber-optic networks to support internet and mobile communications. More recently, Corning has expanded its presence in solar energy, producing materials used in the manufacturing of solar cells.
Although Corning's diverse end markets have long provided a stable industrial foundation, management is repositioning the company to capitalize on accelerating demand from artificial intelligence. At its recent Investor Day, leadership expanded the company's "Springboard Plan." Management is targeting an annualized sales run rate of $30 billion by the end of 2028 and $40 billion by the end of 2030. These goals are supported by multi-year supply agreements with major cloud providers, including Amazon, and a strategic partnership with NVIDIA. Together, these relationships give Corning a meaningful role in building the physical infrastructure required to support AI.
As part of our investment process at Beese Fulmer, we look for companies that are leaders in their industries, with clearly defined economic moats that can support long-term success. In our view, Corning's moat comes from decades of expertise in glass science and optical physics. Replicating ultra-pure optical fiber or damage-resistant glass at global scale requires significant capital, specialized manufacturing plants, and technical expertise that is difficult to reproduce.
There is also a stickiness to Corning's business that we like. Its products are often engineered directly into a customer's network or device. Once that happens, changing suppliers isn't necessarily simple. Products have to be tested, qualified, and integrated without disrupting the end product. We believe these switching costs help support long-term customer relationships and provide some visibility into future demand.
Corning also displays several financial characteristics that fit well with our quality investment philosophy. The company is balancing its cyclical hardware exposure with long-term, multi-year supply agreements, some of which include customer commitments that help support Corning's investments in additional capacity. While this doesn't eliminate the cyclicality of the business, we believe it can provide better visibility into future revenues and earnings.
Profitability is another important part of the thesis. As higher-margin optical communications become a larger piece of Corning's business, the company should benefit from both higher sales and better operating leverage. According to FactSet, management is targeting operating margins of at least 20% over time. If Corning can deliver on its sales targets while expanding margins, earnings could grow considerably faster than revenues over the next several years. That combination is what makes the opportunity particularly interesting to us.
Of course, there are risks to the bull case. Corning is making significant investments today based on the expectation that AI infrastructure spending will continue to grow. If hyperscalers slow their spending, data center construction cools, or AI architecture develops differently than expected, some of that anticipated demand may not materialize. Competition and pricing pressure are also risks, and Corning still has exposure to several cyclical businesses outside of optical communications. Management's 2028 and 2030 targets are ambitious. We believe Corning has a path to achieving them, but they are targets.
On capital allocation, management appears to be striking the right balance, putting significant capital back into domestic manufacturing to capture growing demand while maintaining a disciplined balance sheet and continuing to return capital to shareholders through dividends.
In our view, Corning has evolved into an increasingly important part of the infrastructure behind the digital economy. The company has the technology, manufacturing expertise, customer relationships, and financial characteristics we look for in a quality business. AI has created a significant new growth opportunity on top of that existing foundation. There are risks to the thesis, particularly if AI infrastructure spending slows, but we believe Corning remains an attractive long-term investment for our clients.
Past performance is not indicative of future results. The material above has been provided for informational purposes only and is not intended as legal or investment advice or a recommendation of any particular security or strategy. The investment strategy and themes discussed herein may be unsuitable for investors depending on their specific investment objectives and financial situation. Information obtained from third-party sources is believed to be reliable though its accuracy is not guaranteed, Beese Fulmer Private Wealth Management ("Beese Fulmer") makes no representation or warranty as to the accuracy or completeness of the information, which should not be used as the basis of any investment decision. Information contained on third-party websites that Beese Fulmer may link to is not reviewed in their entirety for accuracy and Beese Fulmer assumes no liability for the information contained on these websites. Opinions expressed in this commentary reflect subjective judgments of the author based on conditions at the time of writing and are subject to change without notice. No part of this material may be reproduced in any form, or referred to in any other publication, without express written permission from Beese Fulmer. For more information about Beese Fulmer, including our Form ADV brochures, please visit https://adviserinfo.sec.gov and search for our firm name.